Why this matters now
On August 25, 2026, CBAK Energy Technology Limited (NASDAQ: CBAT) announced it had secured a large-scale battery cell order from one of India's leading two- and three-wheeler manufacturers, with an estimated value of approximately US$96 million.
Set that against the company's market capitalization of $76.55 million at the August 27, 2026 close. A single customer order is worth roughly a quarter more than the entire equity value of the business booking it. At a large manufacturer that ratio would be a rounding error. Here it is the whole story.
The market's response is the second half of the story. Shares closed at $0.8635 on August 27, down 7.06% on the session, against a previous close of $0.9291. Over one year the market capitalization has fallen 10.7% while trailing twelve month revenue rose 50.5%. A company growing revenue by half and winning orders larger than itself is being valued at less than it was a year ago. That gap is not an oversight. It is a judgment about what the revenue is worth.
Second quarter results are due September 1, 2026, which makes the margin line in that release the most consequential number of the next quarter.
What the company does
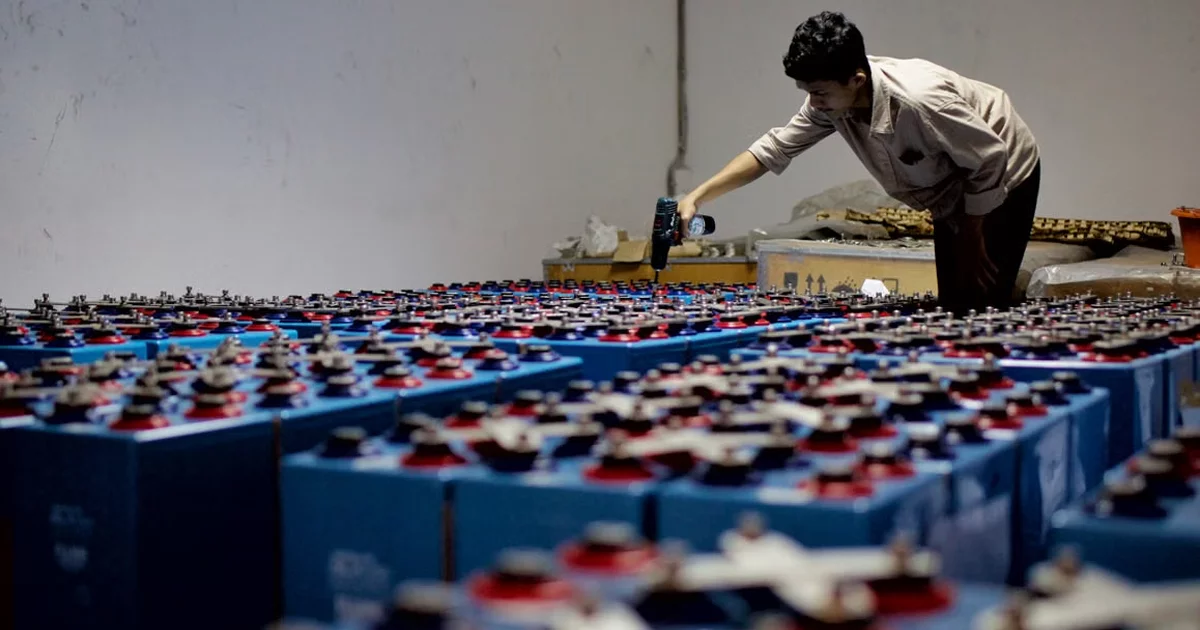
CBAK manufactures rechargeable batteries, primarily cylindrical lithium-ion cells, and increasingly sodium-ion cells. Cylindrical means the familiar metal tube format rather than the flat pouch used in most phones. Its cells go into electric bicycles, tricycles, light electric vehicles, buses, and stationary energy storage systems.
The business runs in two segments. The CBAK segment makes and sells the cells themselves. The Hitrans segment makes nickel-cobalt-manganese precursor and cathode materials, which are the chemical inputs that go inside a cell. Owning both means CBAK captures margin at two points in the chain, and also carries inventory and price exposure at two points.
Model numbers matter in this business because they denote physical dimensions and therefore which applications a cell can serve. The 32140 cell, roughly 32mm by 140mm, is CBAK's growth product. The 26650 is the smaller format it is adapting for backup power in data centers.
The company is based in Dalian, China, employs 1,739 people, and completed a redomiciliation to the Cayman Islands on June 23, 2026, with its Nasdaq listing and ticker unchanged.
CBAK Energy Technology Limited (NASDAQ: CBAT)
Cylindrical lithium-ion and sodium-ion cell manufacturer, Dalian, China
Revenue, net income and market capitalization per stockanalysis.com, retrieved August 28, 2026, reflecting the August 27, 2026 close. Order value per the company's press release dated August 25, 2026.
The bull case
The revenue growth is large and it is real. Trailing twelve month revenue reached $229.87 million, up 50.5%. Per the fourth quarter 2025 results released March 30, 2026, quarterly revenue was $58.8 million against $25.37 million in the comparable prior-year quarter. This is not a development-stage company describing a plan. It is shipping product at scale into multiple continents.
Unit volumes are confirming the revenue. Per a company release dated August 13, 2026, shipments of the Model 32140 cell more than doubled year over year in the first seven months of 2026, surpassing full-year 2025 volume. Per an April 13, 2026 release, CBAK ranked second in China for 26650 and 26700 cylindrical cell shipments and third for the 32140. Volume growth that outpaces the calendar, in a domestic market as competitive as China's, is harder to manufacture in a press release than revenue is.
There is a credible second demand curve forming. Per releases dated July 6 and July 14, 2026, CBAK is developing and testing full-tab 26650 lithium iron phosphate cells for backup power in AI data centers. Data center backup is a different customer, a different margin structure and a different cycle from electric two-wheelers. Whether it converts is unknown. That it exists means the company is not solely exposed to light electric mobility pricing.
The bear case
- Gross margin is collapsing as volume rises. Per the fourth quarter 2025 results, gross profit was $4.28 million on $58.8 million of revenue, a gross margin of 7.3%, against $3.31 million and a 13.1% margin a year earlier. Revenue more than doubled while gross profit rose about 29%. Selling more at a thinner spread is not the same as growing, and at 7.3% there is very little room between the factory gate and a loss.
- The company is losing money at scale. Trailing twelve month net income was negative $17.09 million, or $0.19 per share, on $229.87 million of revenue. A business this size that cannot convert half a billion renminbi of quarterly sales into profit has a structural pricing problem, not a scale problem, and scale will not fix it on its own.
- The $96 million order names no customer and no schedule. The release describes one of India's leading two- and three-wheeler manufacturers and an estimated value. It does not name the counterparty, state the delivery period, or disclose pricing terms. At 7.3% gross margin, a $96 million order produces roughly $7 million of gross profit before any operating cost. The headline number and the economic contribution are very different figures, and only one of them was in the release.
- Verification is harder here than at a domestic issuer. Operations are in Dalian, the corporate domicile moved to the Cayman Islands on June 23, 2026, and the largest disclosed customers are in India and Southeast Asia. None of that is improper, and the Nasdaq listing is unchanged. It does mean that a reader checking a customer relationship or an inventory balance has fewer independent routes to do so than they would with a US operating company, and that discount is part of why the market capitalization has fallen while revenue has risen.
- The risk that cuts against this view: if the September 1 results show gross margin recovering toward the low teens while revenue holds, the entire bear case above collapses into a ramp-cost story that has now passed. Margin at this company is a variable, not a constant, and one good quarter on that line would reprice the equity faster than any order announcement has.
Financial snapshot
Fourth quarter, year over year
In millions of dollars. Bar length is proportional to value.
Source: fourth quarter and full year 2025 unaudited results, released March 30, 2026.
Fourth quarter gross margin, year over year
As a percentage of revenue. Bar length is proportional to value. Revenue more than doubled across these two periods.
Source: fourth quarter and full year 2025 unaudited results, released March 30, 2026. Gross profit was $4.28 million against $3.31 million a year earlier.
On share count and liquidity: shares outstanding stand at 88.65 million. Average daily trading was 231,381 shares on the August 27, 2026 session, which at $0.8635 is roughly $200,000 of daily dollar volume. That clears the threshold below which a position cannot be exited cleanly, but not by a wide margin, and it is worth knowing before reading any of the above as actionable.
Catalysts to watch
- Second quarter 2026 results, September 1, 2026. Watch gross margin first, revenue second. A margin holding near 7% while revenue grows tells you the growth is being bought.
- Confirmation of the India order in reported revenue. The first checkable evidence would be a disclosed delivery schedule or a customer concentration line in a subsequent filing.
- Nanjing Phase II capacity. Per an August 20, 2026 release, the company is expanding Model 32140 capacity there. Capacity additions at thin margin are a bet that volume fixes the spread.
- Conversion of the data center backup power program from customer testing, reported July 14, 2026, into a named order.
The bottom line
CBAK is shipping real volume, growing revenue by half, ranked in the top three in China for its cell formats, and has just announced an order worth more than the company itself.
It is also selling that volume at a 7.3% gross margin against 13.1% a year earlier, losing $17.09 million over twelve months, and watching its market value fall 10.7% over the period in which its revenue rose 50.5%. The order names no customer and carries no schedule.
We label this Neutral. The revenue is not in doubt. What the revenue is worth is entirely in doubt, and one line in one filing settles it. The Desk treats the $96 million order as volume, not as profit. What to watch is gross margin in the second quarter results on September 1, 2026.
CBAK Energy Technology Limited (NASDAQ: CBAT)
Price data as of: August 27, 2026 close, 4:00 PM EDT.
Income statement data as of: trailing twelve months, and the fourth quarter 2025 results released March 30, 2026 for the margin figures.
Price, market capitalization, shares outstanding, 52-week range, volume, revenue and net income per stockanalysis.com, retrieved August 28, 2026. Figures are a point-in-time snapshot as of the dates shown and will change. This is not a valuation opinion, a price target, or a recommendation. Balance sheet detail is not included here because the second quarter 2026 results had not been released at the time of writing. Verify against current data before acting on anything in this piece.
Disclosure
This article is independent editorial content and reflects the author's opinion and analysis as of the date of publication. It is not investment advice and should not be relied on as the basis for any investment decision. MicroCap Desk and its contributors received no compensation of any kind — cash, securities, or otherwise — from any company mentioned, or from any third party, in connection with this article. The author holds no position in any security mentioned. Information is drawn from sources believed reliable but is not guaranteed accurate or complete. Microcap securities carry a high risk of loss. Do your own research. See our full Disclosure.